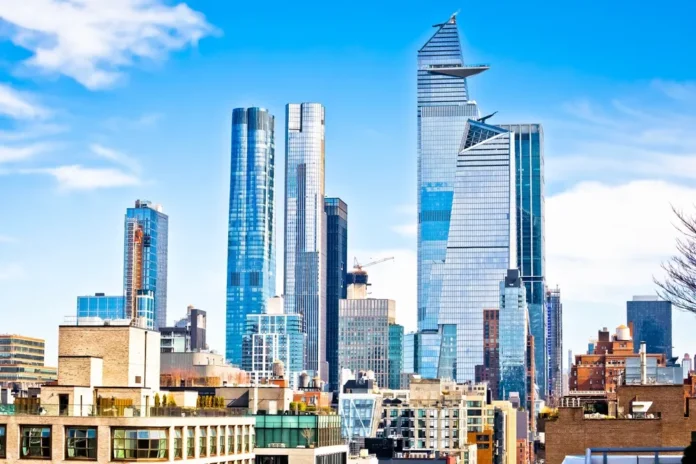
Two years ago, Manhattan’s office market carried vacancy rates around 25 percent, a figure that reflected years of pandemic-era uncertainty and leasing volume that had cratered from a healthy annual pace of 40 million square feet to single digits. Today, according to Bert Rosenblatt, Managing Principal at Cresa’s New York office, that vacancy rate sits closer to 15 percent, driven not by a single catalyst but by demand from industries that barely existed five years ago.
“Last year we rented more than 40 million square feet, and this year is just on fire,” Rosenblatt says. “The first two quarters of this year have been incredibly strong.”
What’s Driving Leasing Volume
The tenant mix powering this recovery looks different from the one that sustained Manhattan office before the pandemic. AI-backed technology firms are taking large blocks of space; Rosenblatt points to Anthropic leasing an entire building in New York as one example of companies that “seemingly have come out of nowhere” and are now committing to major footprints.
Law firms are also expanding, in part because the legal complexity surrounding AI has generated substantial litigation work. Financial technology tenants and cryptocurrency firms round out the demand picture. Rosenblatt notes that crypto “wasn’t really a thing before Covid” in terms of office leasing activity, and now represents a meaningful source of deals.
The underlying driver, in his view, is talent concentration. Companies are locating where they can recruit, and young professionals want to be in New York. “All of these companies want to be where their talent is and where they can find the most talented people,” he says.
The Return-to-Office Effect
Rather than interest rate cuts – which Rosenblatt had flagged as a potential catalyst in 2024 – the recovery was propelled by employers concluding that remote work was not delivering results. “Companies of all shapes and sizes, of all industries realized that they can’t work from home, that you need to be in an office, that you need to be around other people, and they came back in large numbers,” he says.
Repeated studies on productivity reinforced this conclusion, and training, mentoring, and relationship-building proved difficult to replicate virtually. The result has been larger footprints rather than smaller ones; tenants are growing headcount and adding space rather than consolidating.
Trophy Rents Are Climbing Fast
At the top of the market, pricing has moved into territory Manhattan has never seen. The previous high-water mark for office rent in the city was around $300 per square foot. Several recent deals have closed at $350, and one transaction was reported at $400 per foot.
“It’s a very, very small section of buildings that are going up that quickly,” Rosenblatt acknowledges, “but that’s what’s happening.” In one new building, a broker fielded three or four offers above asking rent for a fully built-out space, a bidding-war dynamic that remains limited to select spaces but shows how tight supply has become for move-in-ready inventory in top-tier buildings.
For tenants weighing whether to wait for better conditions, the trajectory points in one direction. “There was one landlord I was talking to; they’re raising their rates every week,” Rosenblatt says.
Class B and C Are Filling Differently
The lower tiers of the market are recovering through a different channel. Nonprofits and creative-industry tenants – talent agencies, firms tied to Broadway, film, and television production – are absorbing Class B and C space. Meanwhile, roughly 10 million square feet of older office space has been converted to residential use, permanently removing supply from the market and contributing to the declining vacancy rate.
Rosenblatt says this conversion trend has had more impact than he anticipated two years ago. “I didn’t think it was going to be that big a deal,” he says, “but I think it really is.” Downtown Manhattan has seen the heaviest concentration of these conversions.
The combination of creative tenants filling lower-tier space and residential conversions removing it means the vacancy improvement is not concentrated in trophy buildings alone; it extends across the market’s quality spectrum.
What Could Disrupt the Trajectory
The main risk Rosenblatt identifies is not on the demand side but the cost side. High interest rates mean building owners facing refinancing may be forced to sell, though he frames that as a transfer of ownership rather than a market problem, since buyers will step in. The larger concern is construction costs: tenant improvements financed at high rates push occupancy costs up, and at some point tenants may resist paying more.
So far, that resistance has not materialized. “People are just paying more,” he says. “That’s what’s happening. The customer is paying more.”
For tenants with leases expiring within the next year, Rosenblatt’s advice is direct: “They should get going, because I think it’s just going to be more expensive, not less expensive.”
What Comes Next
Rosenblatt says most tenants he speaks with are more confident than they were a year ago, citing a generally healthy economy and continued hiring, particularly in AI-related roles. He notes that AI appears to be adding jobs in New York rather than eliminating them, though the workers being hired may have different skills than those being displaced elsewhere.
The pockets of softness that remain – the Garment District, parts of downtown Manhattan – have not prevented the broader market from tightening. With leasing volume running above the 40-million-square-foot threshold that defines a healthy year, and vacancy continuing to compress, tenants delaying decisions face a narrowing set of options at rising prices.
About the Expert: Bert Rosenblatt is Managing Principal at Cresa’s New York office, specializing in commercial office tenant representation in Manhattan.
This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.